
Drone Finance
Finance for commercial, agricultural spray, inspection, mapping and media drones
Drone finance lets Australian businesses spread the cost of commercial drones, payloads and support gear over a fixed term instead of paying upfront.
We arrange funding from $5,000 to $250,000 and beyond across 50+ lenders for spray contractors, farmers, inspection operators and production companies, with batteries, chargers and software often bundled into the same facility.
Our Lenders









































What Our Clients Say About Us


How Drone Finance Works
Drone finance is usually written as a chattel mortgage over two to four years. You own the drone from day one, the lender takes security over it, and repayments run over a fixed term. Because drone technology moves quickly and resale values drop faster than most equipment, lenders weigh your business and experience as heavily as the aircraft itself.
That is the key difference between drone finance and financing something like an excavator. A five year old excavator still has a strong resale market. A five year old drone is often two or three generations behind and worth a fraction of what was paid. Lenders know this, so terms are generally shorter, balloon payments are small or not used at all, and approvals lean on your trading history, your bank statements and the work the drone will be doing. The upside is that commercial drones are almost always bought through authorised dealers with a clean tax invoice and serial numbers, and agricultural spray drones from major brands now have an active used market, which gives lenders more comfort than they had a few years ago.
Most files run as a chattel mortgage, and GST registered businesses can generally claim the GST on the purchase price through their BAS. Finance leases and hire purchase are also available, and your accountant can confirm which suits your tax position. A balloon payment is optional where the lender allows one: some clients use a small balloon to keep repayments lower, others prefer to pay the drone off in full before the next upgrade. Drones sit within our broader equipment finance range, and the same principle applies across it: the right lender for the asset makes the approval.

What You Can Finance with Drone Finance
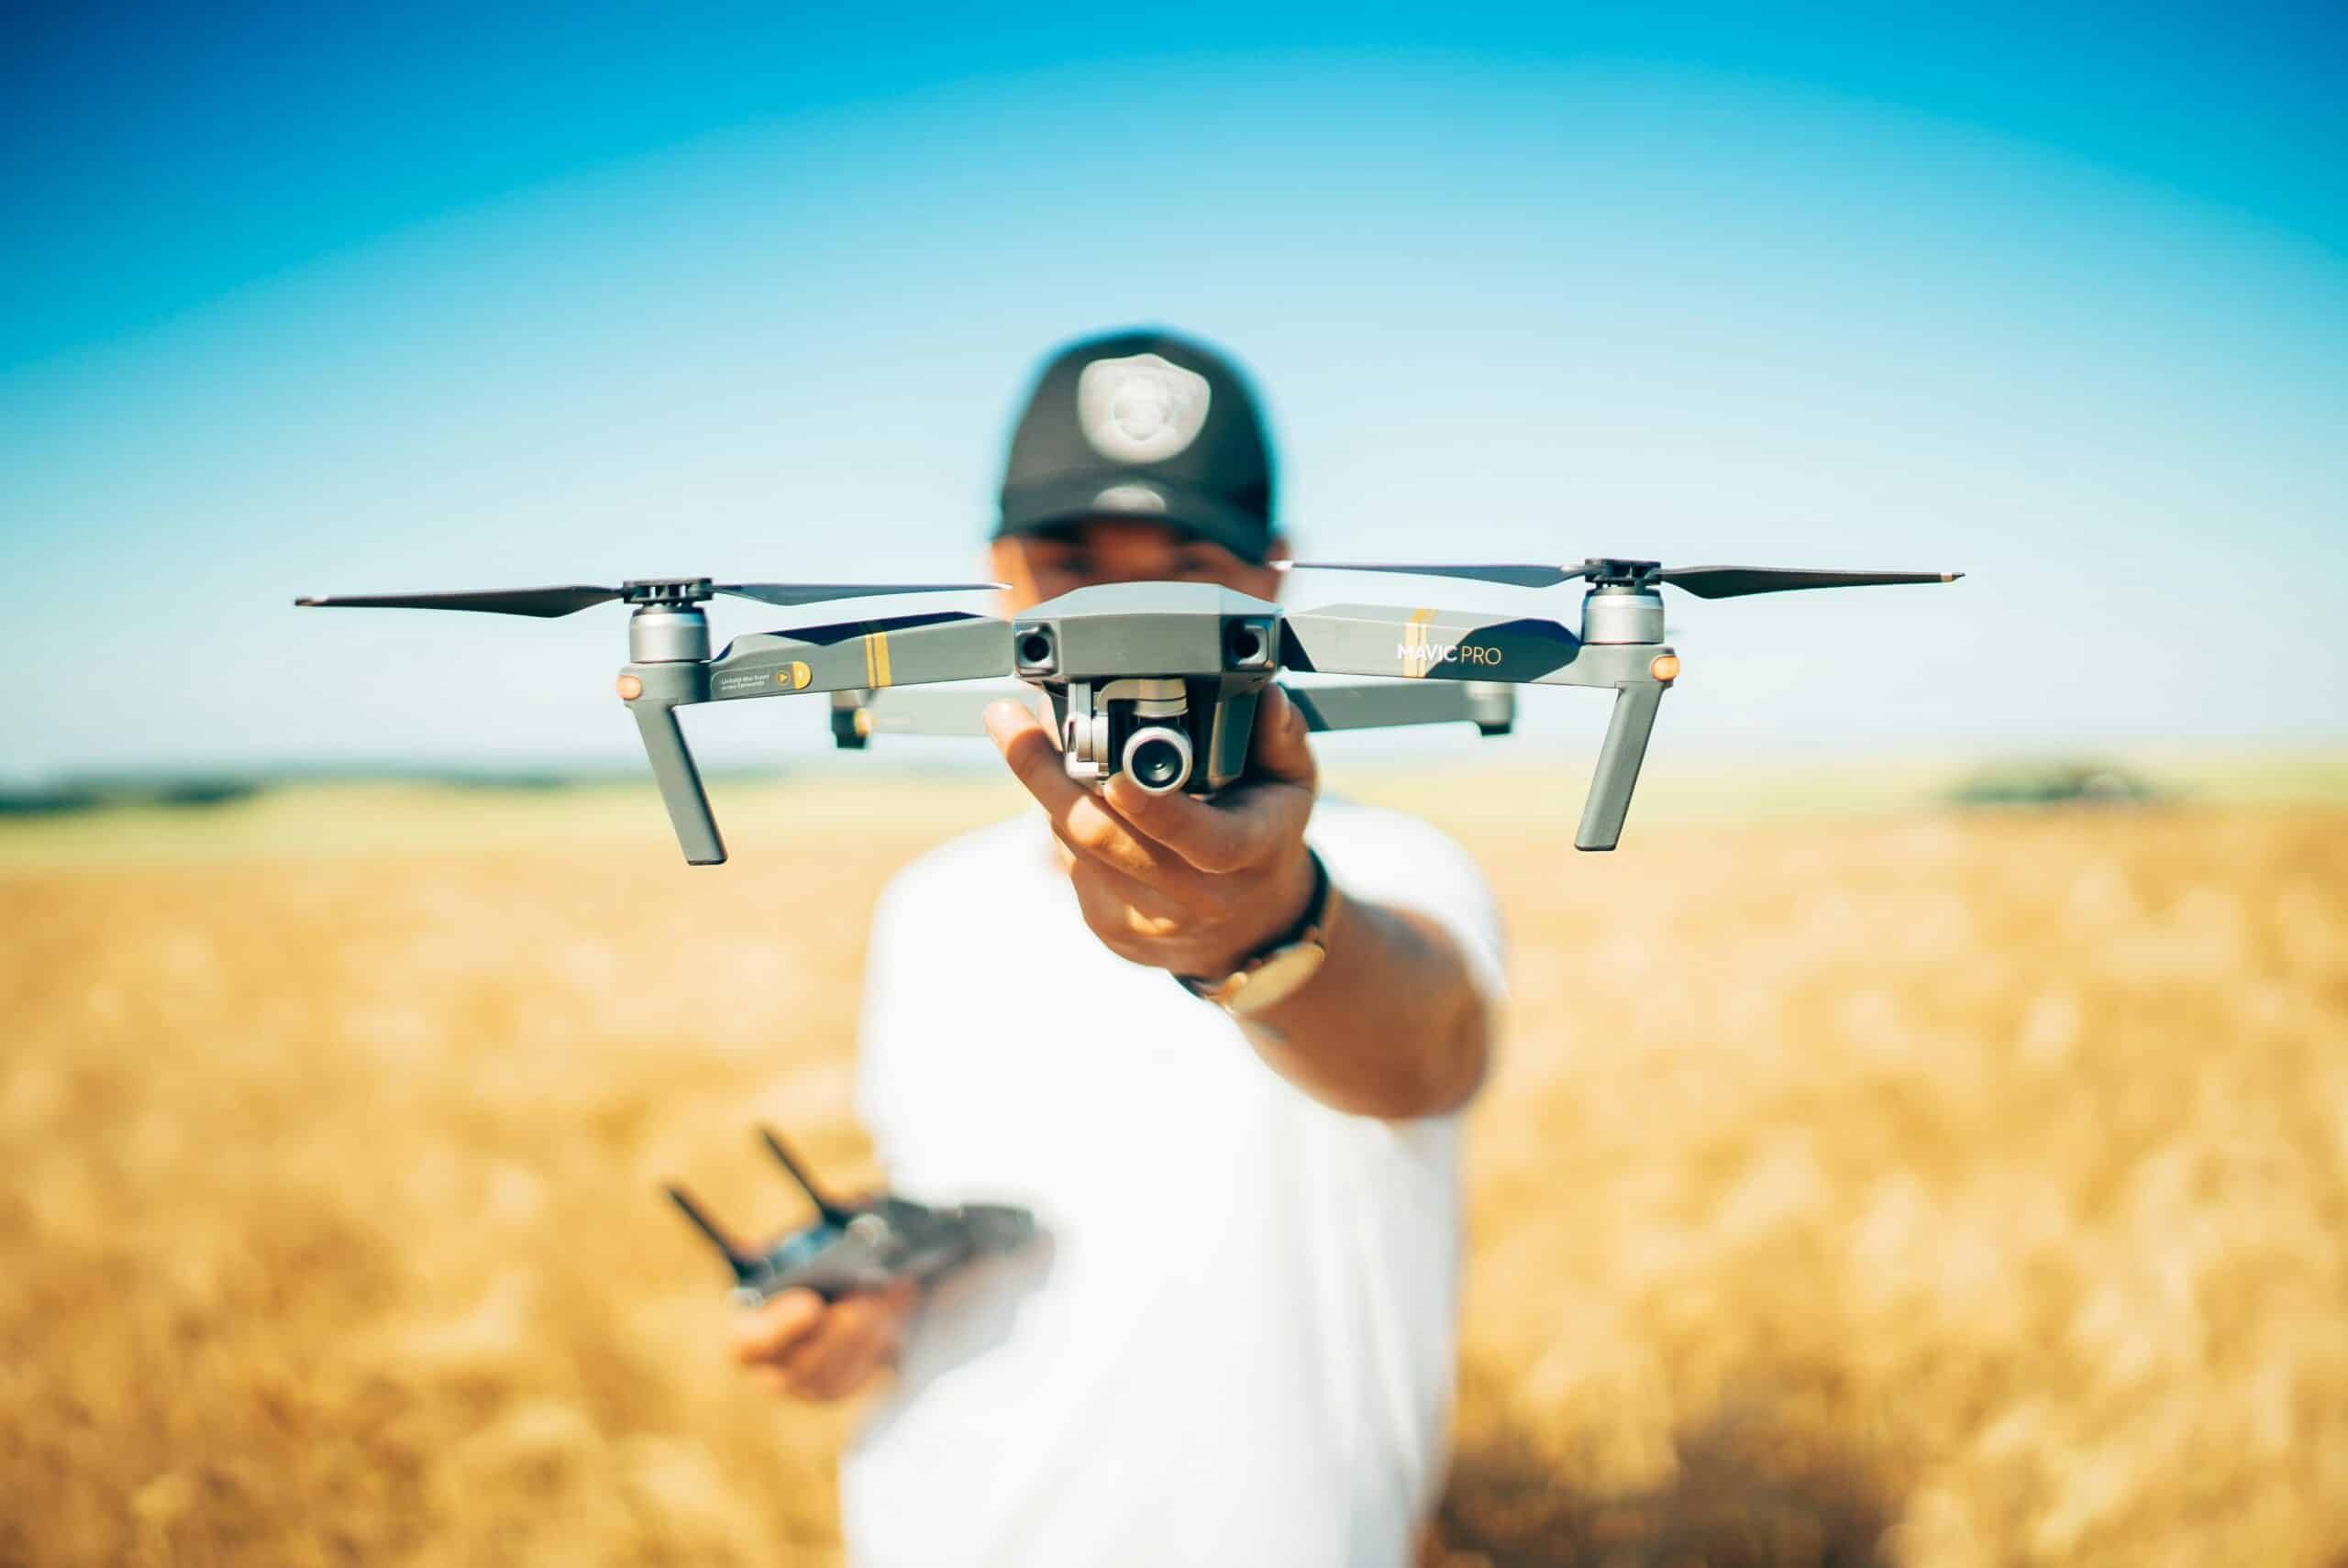
Almost any drone, payload or support equipment used to earn income can be financed, from brands like DJI, XAG, Autel, Wingtra and Freefly. Pricing runs from around $15,000 for an enterprise inspection drone through to $120,000 or more for a full LiDAR mapping setup. Bundling the aircraft and everything it needs into one facility is usually the cleanest approach.
Agricultural Spray and Spreading Drones
Spray drones such as the DJI Agras and XAG ranges for crop protection, weed control, spreading seed and fertiliser, and spot spraying on country that ground rigs can't reach. A complete agricultural drone kit typically runs $30,000 to $80,000 once batteries, chargers and a generator are included. These are the most common drone files we see, and they carry the strongest lender appetite of any drone category.
Inspection and Thermal Drones
Enterprise drones with zoom and thermal payloads for inspecting roofs, solar farms, power lines, towers, bridges and industrial plant, as well as security and emergency work. Enterprise inspection platforms with payloads usually sit between $15,000 and $60,000.
Mapping and Survey Drones
Multirotor and fixed wing VTOL drones with photogrammetry, multispectral or LiDAR payloads for mapping, volumes, crop health and survey work. Fixed wing mapping drones start around $50,000, and LiDAR setups can run $40,000 to $120,000. If the drone is part of a wider survey kit with total stations and GNSS gear, our surveying equipment finance page covers how lenders assess the whole package.
Cinema and Media Drones
Heavy lift camera drones, gimbals and cinema payloads for film, television, real estate and events. Professional cinema rigs generally run $20,000 to $60,000 depending on the camera and lens package.
Batteries, Chargers, Generators and RTK Base Stations
The support gear often costs as much as the drone. Spray operators typically need several sets of batteries, rapid chargers and a generator to keep flying all day in the paddock, plus an RTK base station for accuracy. These are best financed with the drone rather than paid from cash flow. Larger generators can also be financed on their own through generator finance.
Software, Payloads and Accessories
Perpetual licences for mapping and processing software bought upfront, extra payloads and cameras, spreader attachments, cases, controllers and prepaid enterprise care plans can often be included, within the limit each lender sets on non equipment costs. Monthly subscriptions are generally paid as ongoing operating costs rather than financed.
Drone Fleets
Operators adding several drones at once, or building out a fleet over time, can often have the purchase structured as one approval rather than separate applications for each aircraft.
Who Drone Finance Is For
Drone finance suits any Australian business using drones commercially to earn income or cut costs, from a single spray drone on a family farm through to a multi aircraft inspection business. Each profile below is assessed differently by lenders, which is why matching the file to the right funder matters.
Farmers and agricultural businesses. Growers bringing spraying and spreading in house to cut contractor costs and get onto wet or steep country when ground rigs can't. Drones often sit alongside tractors and sprayers in the same equipment plan, and we finance those through agricultural machinery finance. Seasonal repayments matched to harvest or spray season cash flow are available with some lenders.
Spray contractors. Operators running one or more spray drones for hire across a region. Lenders look at your time in the industry, your existing client base and your licensing. Contractors expanding from one drone to two or three are a common file.
Inspection, mapping and survey operators. Businesses inspecting infrastructure, mapping sites or running drone data services for construction, mining, energy and local government clients. Contract work or a steady client list behind the purchase strengthens the file considerably.
Film, media and real estate businesses. Production companies and content businesses using cinema drones as part of their core kit.
New operators. Plenty of pilots start their own drone business after working for someone else, or after getting licensed while running a farm or another business. Lenders are tighter on new ABNs for drones than for assets with deeper resale, but industry experience, your licences, work already lined up and a deposit or property ownership all help. We regularly arrange new business finance for operators in exactly this position. Bad credit is workable too: prior defaults or judgments narrow the lender pool rather than close it.
Why Use a Broker For Drone Finance
Lender appetite for drones varies more than for almost any other equipment type. Some funders treat commercial drones as income producing equipment and fund them every week, others class them as technology with weak resale and cap the term or decline them outright. A broker matches your file to a lender that understands drones, before an application goes anywhere.
The differences show up in the detail. One lender will include batteries, chargers and a generator with the drone, another will only fund the aircraft. Some are comfortable with a new spray contractor on the strength of their licences and experience, others want two years of trading. Some offer seasonal repayments for agricultural buyers, most don't. Private sales of used drones will be declined by plenty of lenders and approved by a few. Knowing which lender sits where is the difference between a clean approval and a wasted enquiry on your credit file.
Dealer finance is worth comparing too. Drone dealers increasingly offer their own finance plans, and some are genuinely competitive, but a low headline number can be funded through a higher price or come with conditions on the term or upgrade path. Ask the dealer for the cash price and compare the total cost of both options. We are happy to run that comparison, and if the dealer offer comes out ahead, you should take it.
We also handle the work that slows drone files down: confirming dealer invoices and serial numbers, bundling the aircraft, batteries, payloads and software correctly, and coordinating settlement with the dealer so your drone is released in time for the season.
Get a Free Drone Finance Quote
Tell us what you need to power and we will match your file to the right lender from our panel of 50+ funders, with no obligation and no impact on your credit score.
Getting Drone Finance
Step 1: Tell us what you're buying
Send through the dealer quote for the drone and everything that goes with it, along with a quick overview of your business, your licences and the work the drone will be doing. No paperwork upfront. We assess lender fit before asking for a single document.
Step 2: We match you to the right lender
We identify the lender whose policy best fits the drone, the support gear, your trading history and your credit profile, structure the package correctly, and submit with a clear credit narrative on anything complex.
Step 3: Get approved and settled
Straightforward files are typically approved within 24 to 72 hours. Once documents are signed, settlement is paid directly to the dealer and your drone is released, ready for the next job or the start of the season.
Drone Finance FAQs
Yes. Drones bought for business use can be financed like other income producing equipment, with the drone acting as security. Most files are written as a chattel mortgage over two to four years. Agricultural spray drones, inspection drones, mapping drones and cinema rigs can all be funded, along with the batteries, payloads and software that go with them.
Agricultural spray and spreading drones, enterprise inspection drones with zoom and thermal payloads, multirotor and fixed wing mapping drones, LiDAR and multispectral survey drones, and heavy lift cinema drones. New and ex demo drones from brands like DJI, XAG, Autel, Wingtra and Freefly are all common. Drones bought for personal or hobby use sit outside business drone finance.
As a rough guide, enterprise inspection drones with payloads run $15,000 to $60,000, agricultural spray drone kits run $30,000 to $80,000 once batteries, chargers and a generator are included, fixed wing mapping drones start around $50,000, and LiDAR setups can run $40,000 to $120,000. Cinema rigs generally sit between $20,000 and $60,000.
Yes, and it is the most common drone file we see. Spray drones from major brands carry the strongest lender appetite of any drone category because there is an active used market for them. The full kit, including spare batteries, rapid chargers, a generator, an RTK base station and spreader attachments, can usually be financed together in one facility.
Usually, yes, when they are bought with the drone. Batteries, chargers, generators, RTK base stations, extra payloads, cases and perpetual software licences can often be bundled into the same facility. Most lenders limit how much of the total can be soft costs such as software, and monthly subscriptions are generally paid as operating costs rather than financed.
Terms typically run from two to four years, and some lenders will go to five on higher value agricultural or mapping drones. Shorter terms are common because drone technology dates quickly. A balloon payment is optional where the lender allows one, and whether to use one is entirely your choice based on cash flow and your upgrade plans.
Not always, but it helps. A remote pilot licence (RePL) and a remotely piloted aircraft operator's certificate (ReOC) show lenders the drone will be operated commercially and legally, which strengthens the file. Agricultural spray operators generally also need chemical application accreditation. We can advise what each lender looks for before you apply.
Yes. Ex demo and used drones bought through authorised dealers are straightforward, particularly with a tax invoice and clear serial numbers. Private sales are harder because lenders want to verify ownership and condition, and older models fall outside some lenders' age limits quickly. We match used purchases to lenders whose policy fits the drone.
Some lenders offer seasonal or structured repayments for farmers and spray contractors, with higher payments during harvest or spray season and lower payments in quieter months. This is not available from every lender, so it comes down to placing the file correctly. We can tell you upfront whether your situation suits a seasonal structure.
Yes. Operators buying several drones at once, or adding aircraft over time, can often have the purchase structured as a single approval rather than separate applications for each drone. Lenders look at your time in the industry, your client base or contracts, and how the existing fleet is being used. This saves time and paperwork as the business grows.
Yes. Lenders are tighter on new businesses for drones than for assets with deeper resale markets, but plenty of new operators get approved. Industry experience, your licences, work already lined up and your personal credit history all count in your favour. A deposit or property ownership widens the lender pool, but neither is always essential.
Yes, bad credit is workable. Prior defaults, judgments or a thin credit file narrow the lender pool rather than close it. Specialist non bank lenders assess the full picture, including what caused the issue and how the business is trading now. A clear explanation and recent bank statements go a long way.
For most files under $150,000 you need an ABN, GST registration, your driver's licence, recent business bank statements (typically three to six months) and the dealer quote or tax invoice. Copies of your RePL, ReOC or chemical accreditation are useful where they apply. Larger files usually need full financials. We tell you exactly what is needed before you provide anything.
It is worth comparing both. Some drone dealers offer their own finance plans, and some are genuinely competitive, but a low headline number can be offset by a higher price or conditions on the term. Ask the dealer for the cash price and compare the total cost of both options. If the dealer offer comes out ahead, take it.
Straightforward files with clean credit and a dealer quote are typically approved within 24 to 72 hours. New ABN files, private sales and larger fleet purchases take longer, usually up to one to two weeks, because they need a fuller credit narrative. Once documents are signed, settlement is paid directly to the dealer so the drone is released in time for the season.
Ready to Finance a Drone
Call us on 0416 960 969 or fill out the form below. We respond the same business day with an honest assessment of your options across 50+ lenders.